Superannuation is Australia's compulsory retirement savings system: your employer pays a percentage of your earnings into a super fund, the fund invests it, and you generally cannot touch it until you reach preservation age. This guide is for employees checking that the right amount is landing in their account, and for small employers working out what they owe each pay run. It covers eligibility, how the calculation works, and the records that prove superannuation was paid correctly.
Key takeaways
- Superannuation is money set aside during your working life, mostly through compulsory employer contributions, and generally preserved until you reach your preservation age and meet a condition of release.
- The super guarantee rate rose to 12% of ordinary time earnings from 1 July 2025, and the ATO publishes the full rate table so you can check the rate that applied in any earlier quarter.
- Employers must pay contributions to the employee's chosen fund electronically through SuperStream. From 1 July 2026, under Payday Super, super is paid with each pay run and must reach the fund within seven business days of payday.
- Fees, insurance premiums and the investment option you sit in all change your final balance, and you can usually switch options inside the same fund without leaving it.
- Keep payslips, annual statements and choice of fund paperwork so you can prove what was paid and when.
What Is Superannuation and How Does It Work in Australia?
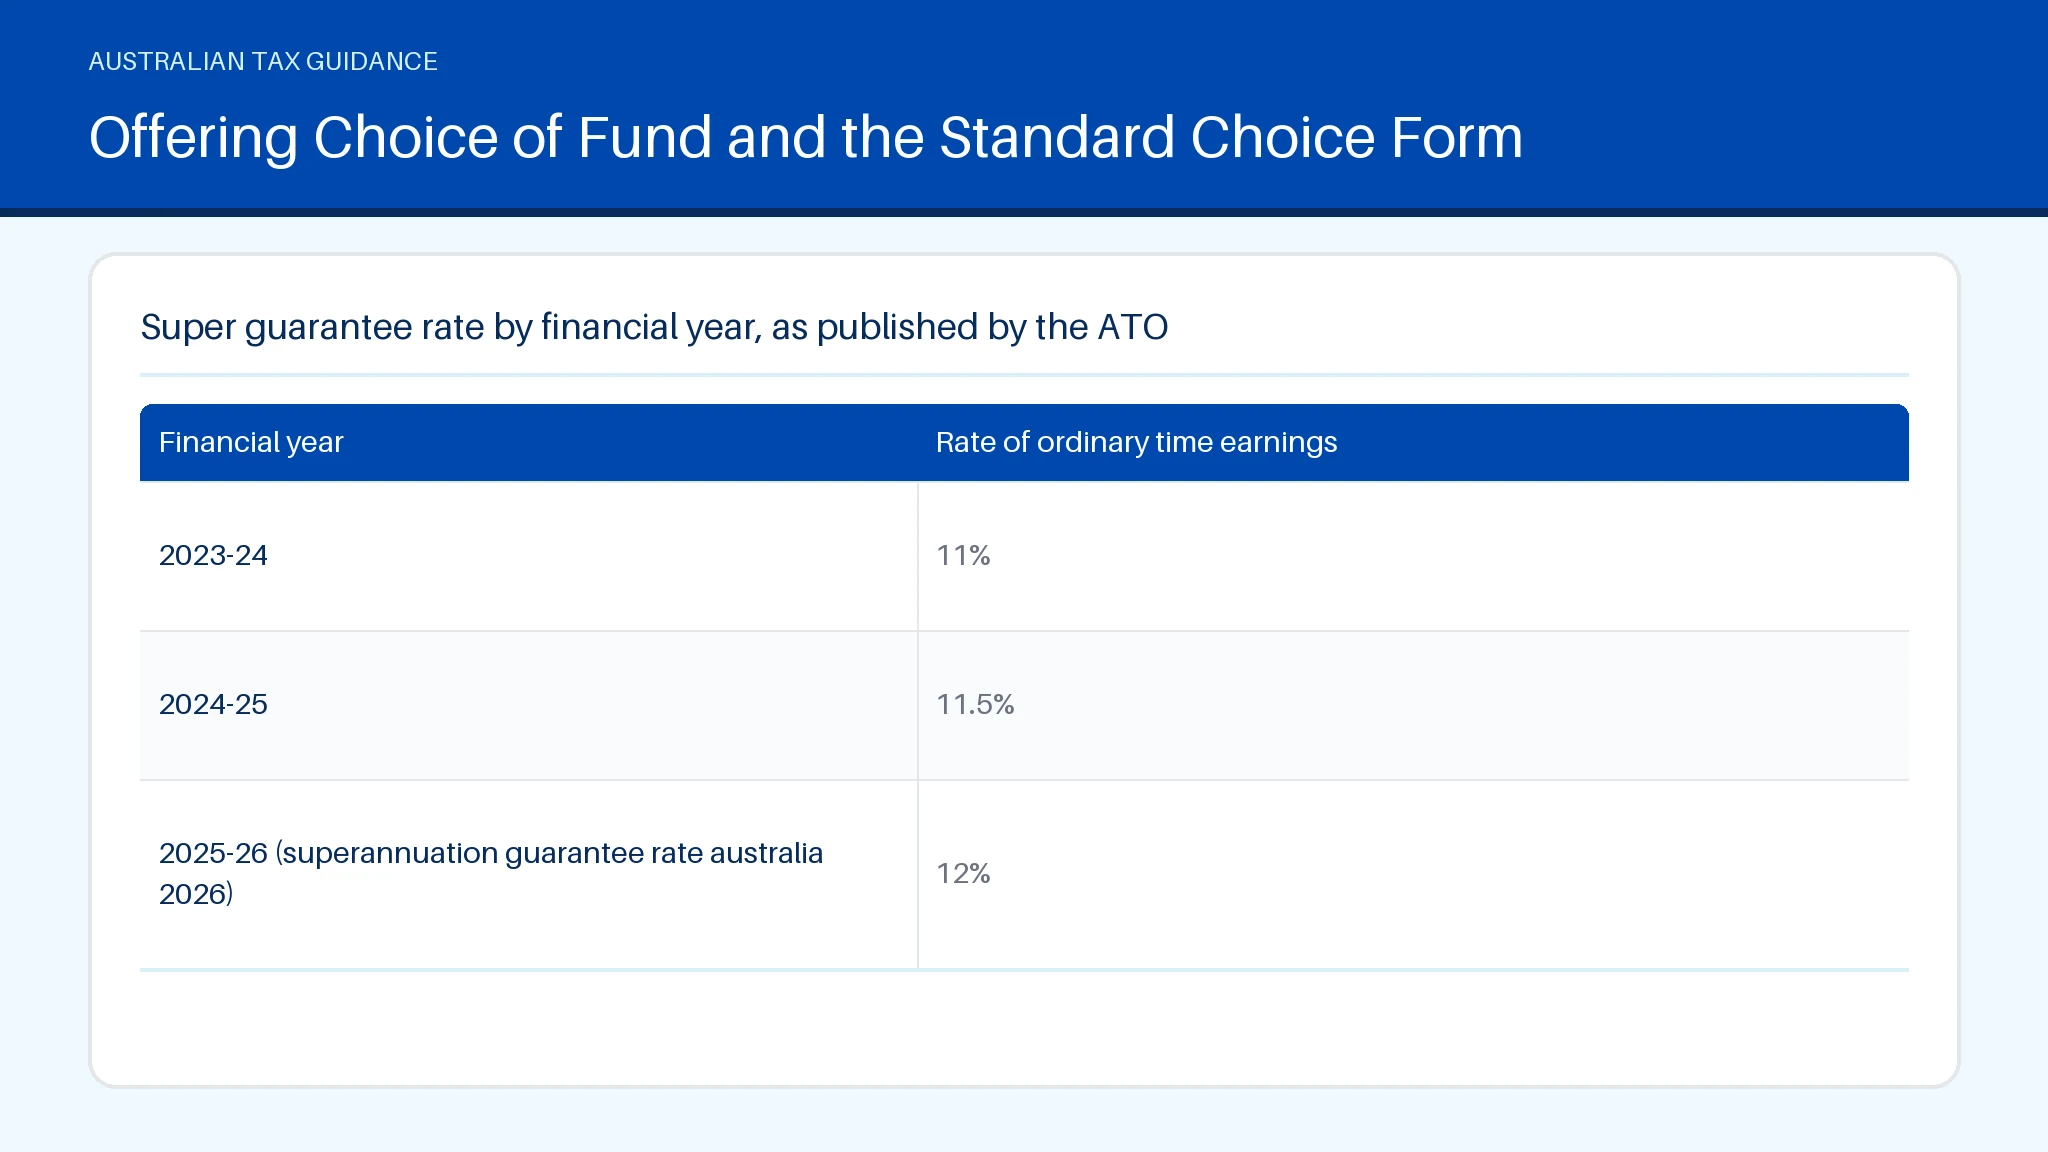
Superannuation works as a two-part machine: a compulsory employer contribution goes in, and a fund invests the balance until a condition of release is met. The current super guarantee is 12% of ordinary time earnings. The ATO's superannuation guarantee rates history shows how the rate stepped up, which matters when you review older quarters.
| Financial year | Rate of ordinary time earnings |
|---|---|
| 2023-24 | 11% |
| 2024-25 | 11.5% |
| 2025-26 | 12% |
Investment Options in Your Super Fund and How to Switch
Your super fund pools your money and buys assets with it: listed shares, bonds, property, infrastructure and cash. The option you sit in decides that mix. Most members start in a MySuper default, and you can invest in a different option, or several, by lodging a switch request with the fund. You can generally choose your own super fund too, unless an enterprise agreement or a defined benefit scheme locks your employer contribution in place. Switching options is free at many funds but crystallises unit prices, so timing matters.
How to Calculate the Super Guarantee Rate for Each Employee
Work out super by multiplying each employee's ordinary time earnings for each pay run by 12%. Ordinary time earnings exclude most overtime but include allowances, commissions and paid leave. Each employee's contribution stops accruing once their earnings for the financial year reach the maximum contribution base, an annual limit from 1 July 2026, so check that figure before running payroll. Contractors paid mainly for labour are treated as employees for super. Confirm the superannuation guarantee rate with the ATO before finalising.
Collecting and Checking Employee Fund and Member Details
Collect the fund's ABN, USI, member number and the employee's tax file number before the first contribution leaves your account. Wrong member details are the most common reason a contribution is returned or lands in the wrong account. If a new starter does not choose a fund, request their stapled fund through ATO online services before you contribute. Reconcile each contribution against the wage record for the pay run it covers so the current superannuation guarantee rate is applied to the right earnings, and keep the employer copy on file.
How to Pay Super Using SuperStream and a Clearing House
Pay super electronically through SuperStream, which sends the payment and the member data together in one standard message. Most employers contribute through payroll software or a clearing house; the ATO's free Small Business Superannuation Clearing House closed on 1 July 2026. From 1 July 2026, under Payday Super, super must reach the fund, not just leave your bank, within seven business days of payday. Late super triggers the super guarantee charge.
Super Fund Fees and How They Reduce Your Balance
Every super fund charges fees. Expect an administration fee (often a flat weekly amount plus a percentage), investment fees deducted from returns, insurance premiums, and transaction or activity fees for things like family law splits. Fees on MySuper products are capped for balances under $6,000, and funds must publish them in a standardised fee template. A percentage-based investment fee grows with your balance, so two members on the same super guarantee rate can end up with very different net outcomes.
Offering Choice of Fund and the Standard Choice Form
Give eligible new employees a Standard Choice Form within 28 days of starting, and again within 28 days of any request. Australian employers must act on a valid choice within two months. If an employee nominates a self-managed fund, collect the ABN, bank details and an electronic service address before the next contribution. Record the wage period each contribution covers. Your contribution records should also show which fund each amount went to.
How to Check Your Super Statement and Confirm Correct Payment
Check super by comparing your payslip year to date figure with the contribution amounts shown in ATO online services through myGov, then with your annual fund statement. Funds report contributions to the ATO, so a gap of a quarter or more usually means the employer has not paid. Multiply your ordinary time earnings by the superannuation guarantee rate of 12% to test the amount, or use the superannuation guarantee rates history table for earlier years. Lodge an unpaid super enquiry with the ATO if the numbers do not reconcile.
Summary
Eligibility rests on ATO rules, the calculation is ordinary time earnings times the published rate, and records prove both. This is general information, not personal advice. Deductit's giving and super deduction rules show the ATO source behind each calculation.
You can also use the deduction finder to see which deductions apply to you.
Frequently asked questions
Is superannuation 12%?
Yes. The super guarantee rate is 12% of ordinary time earnings from 1 July 2025, and it is legislated to stay at 12%. Employer contributions are the compulsory amounts your employer pays on top of your wages, and you can add voluntary contributions yourself, either salary sacrifice or after-tax amounts, within the annual caps published by the ATO.
Is $700,000 in super enough to retire in Australia?
It depends on your spending, whether you own your home, your age at retirement and any Age Pension entitlement. Compare your expected annual drawdown against your actual budget rather than a single benchmark figure.
Can my children inherit my superannuation?
Yes, but only certain people. Super paid to a dependant, including a child under 18, is generally tax free; an adult child who is not a tax dependant is usually taxed on the taxable component. A binding death benefit nomination directs the payment.
Can I retire at 60 with $500,000 in super?
Possibly. At 60 you can usually access preserved super once you have retired, and $500,000 supports a modest drawdown that may be topped up by the Age Pension from 67. Model it before you resign.
How many Australians have $1,000,000 in superannuation?
A small minority. ATO taxation statistics show average balances well under $500,000 for most age groups, with seven-figure balances concentrated among older, higher-income members and self-managed funds.