The Medicare levy surcharge is an extra amount of tax the Australian Taxation Office applies to higher income earners who do not hold an appropriate level of private patient hospital cover for themselves and their dependants. It sits on top of the standard Medicare levy. Your income for surcharge purposes, rather than your taxable income alone, decides whether it applies and at what rate, but the surcharge itself is charged on your taxable income plus reportable fringe benefits. The rate is 1%, 1.25% or 1.5% depending on which income tier you fall into.
This guide is for individual Australian taxpayers who want to know whether they will be charged, how the amount is calculated day by day, and what records support the figures they report. It covers singles and family thresholds, how dependent children shift your tier, what happens when hospital cover starts partway through the year or is suspended, and where the Medicare levy surcharge differs from the levy itself.
What you need before you start:
- Your taxable income for the financial year, plus any reportable fringe benefits, reportable employer and salary sacrificed super contributions, net investment or rental losses, and exempt foreign employment income.
- Your spouse's equivalent income figures if you had a spouse for any part of the year.
- The number of dependent children you maintained.
- Your private health insurance statement showing the exact number of days of hospital cover and any excess amount on the policy.
Work through each of those inputs before you try to estimate a rate, because the ATO tests income, family status and days of cover together rather than in isolation.
Key takeaways
- The Medicare levy (generally 2% of taxable income) and the Medicare levy surcharge are separate charges. Almost every Australian resident taxpayer deals with the levy, while the surcharge only applies above the ATO income thresholds when you lack an appropriate level of private patient hospital cover.
- The ATO applies the surcharge at 1%, 1.25% or 1.5% based on income for surcharge purposes, which is broader than taxable income and includes reportable fringe benefits, reportable super contributions, net investment losses and exempt foreign employment income.
- Singles thresholds start above $101,000 and family thresholds above $202,000 for the 2025-26 year, with the family threshold increasing by $1,500 for each dependent child after the first.
- The surcharge is calculated daily, so part year hospital cover only protects you for the days the policy was active. Suspended policies generally do not count as cover.
- Keep your private health insurance statement, income details and dependant records so the amounts on your return match what your insurer reported to the ATO.
What Is the Medicare Levy Surcharge and How Does It Work?
The Medicare levy surcharge is designed to encourage higher earners to take pressure off the public hospital system. The ATO applies it when your income for surcharge purposes exceeds the relevant threshold and you did not hold private patient hospital cover for the full income year. Ambulance only cover, extras only cover and travel policies do not satisfy the test, and neither does a policy with an excess above the ATO limit of $750 for singles or $1,500 for families and couples.
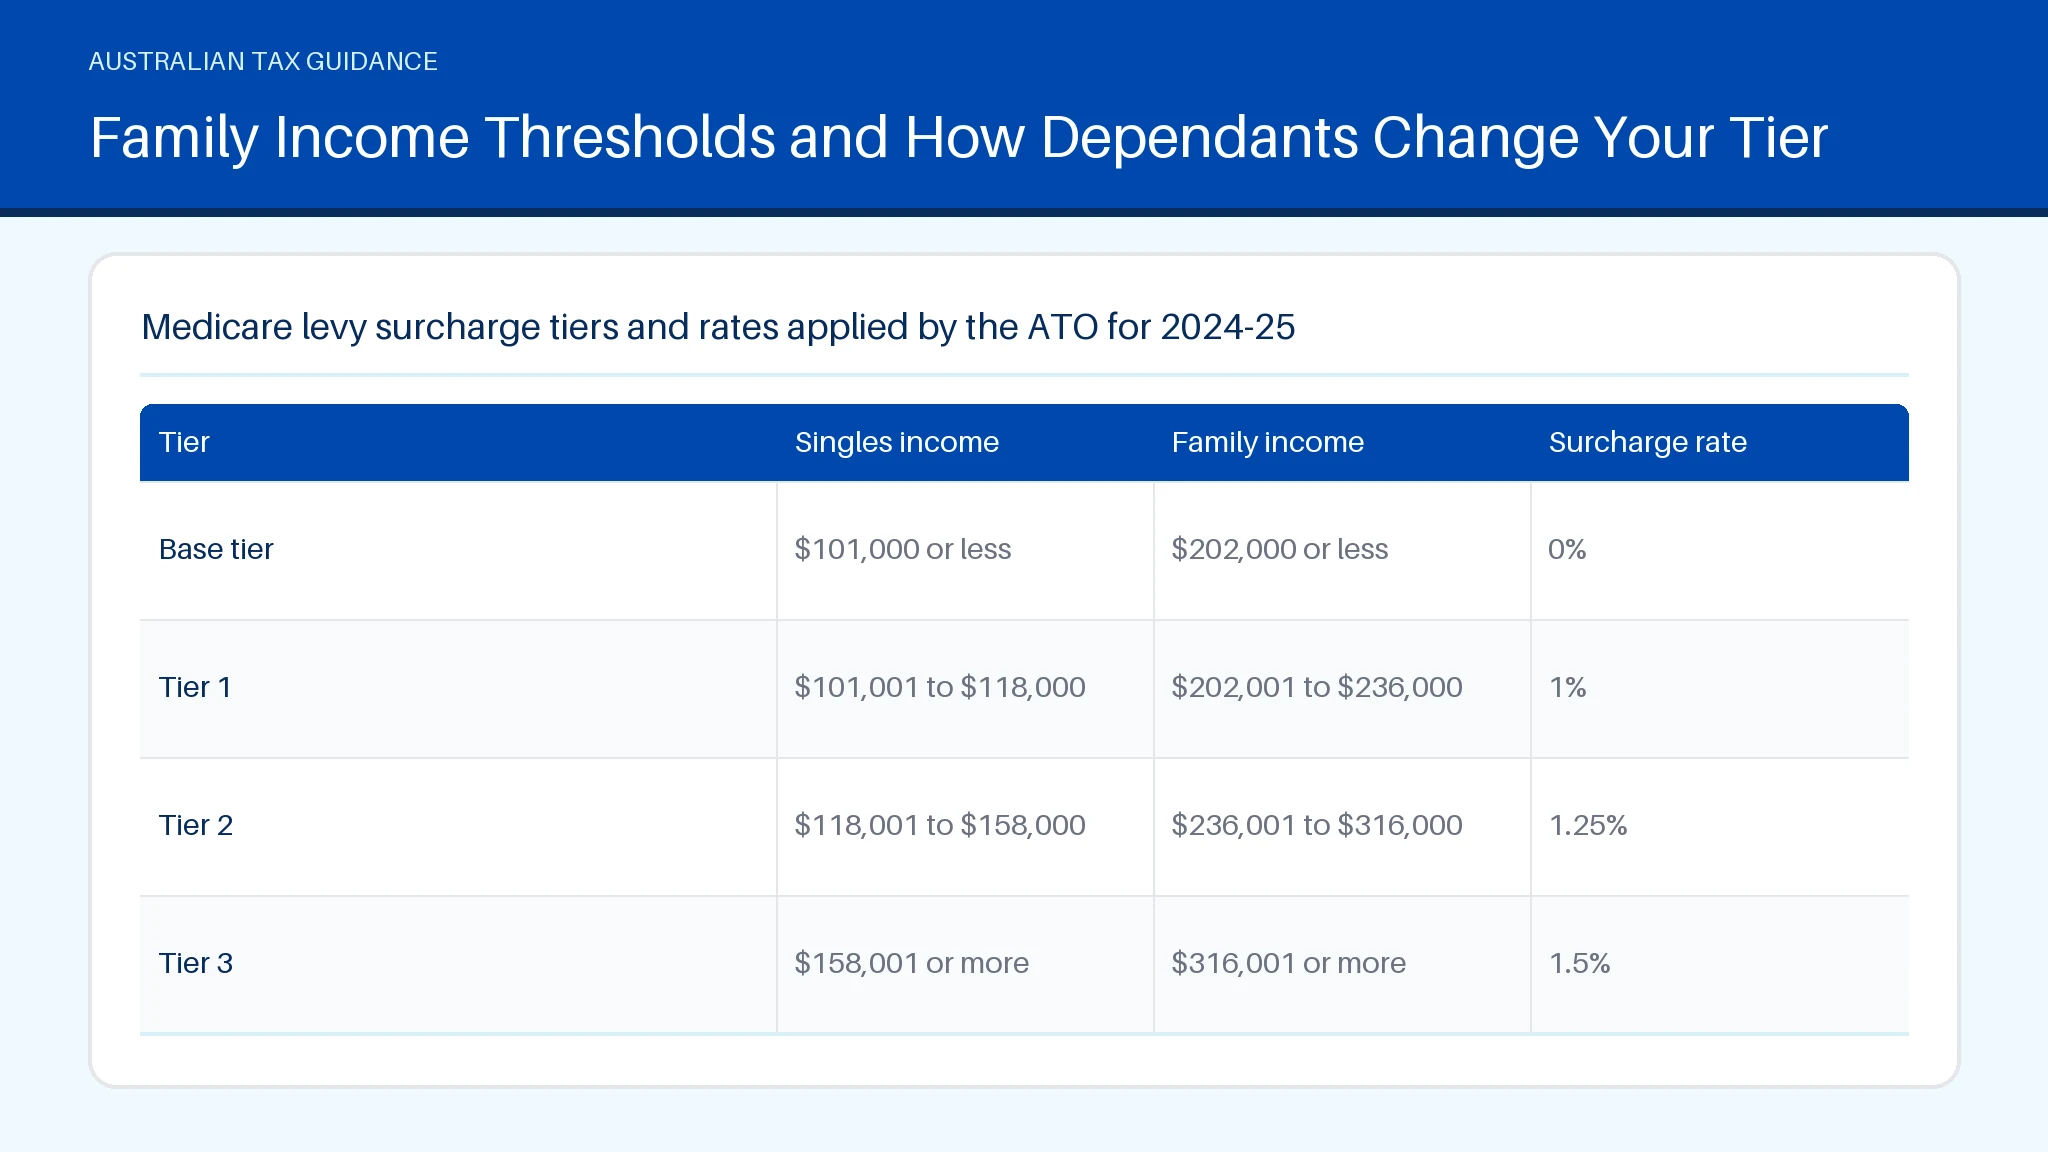
| Tier | Singles income | Family income | Surcharge rate |
|---|---|---|---|
| Base tier | $101,000 or less | $202,000 or less | 0% |
| Tier 1 | $101,001 to $118,000 | $202,001 to $236,000 | 1% |
| Tier 2 | $118,001 to $158,000 | $236,001 to $316,000 | 1.25% |
| Tier 3 | $158,001 or more | $316,001 or more | 1.5% |
The rate that applies is then multiplied by your taxable income plus reportable fringe benefits and apportioned across the days you were uncovered.
When Does a Low Income Reduce or Exempt Your Surcharge?
If your income for surcharge purposes sits in the base tier, the Medicare levy surcharge does not apply at all, regardless of whether you hold hospital cover. That is different from the Medicare levy itself, which has its own low income reduction and thresholds published by the ATO each year.
Two situations catch people out. First, a single person just under the threshold can be pushed over by reportable employer super contributions or a negatively geared rental property, because net investment losses are added back for surcharge purposes. Second, if you had a spouse at any time during the year, the ATO tests your combined income against the family threshold, so a low individual income does not automatically exempt you.
Taxpayers who are not Medicare eligible for part or all of the year may also claim a Medicare levy exemption, which flows through to the surcharge for those days.
Does Hospital Cover Cost Less Than the Surcharge You Pay?
This is the decision most people actually face, and it is arithmetic rather than opinion. Multiply your expected taxable income plus reportable fringe benefits by your tier rate to get the annual cost of the Medicare levy surcharge, then compare it with the annual premium for a basic hospital policy after any private health insurance rebate you are entitled to.
Three factors change the answer:
- Timing. The surcharge is worked out daily, so taking out cover in April only removes the charge for the remaining days.
- Lifetime Health Cover loading. If you first take out hospital cover after 1 July following your 31st birthday, a loading applies to premiums, which raises the long term cost of switching later.
- Value received. The surcharge buys you nothing personally, while a premium buys hospital cover, though usually with waiting periods and an excess.
Run both numbers on your own income before deciding, and re-run them if your income changes mid year.
How the Surcharge Applies to Higher Earners Without Hospital Cover
For a higher earner with no hospital cover for the whole year, the Medicare levy surcharge (MLS) calculation is straightforward: taxable income plus reportable fringe benefits multiplied by the tier rate. Someone in tier 3 with $180,000 of taxable income, no reportable fringe benefits and no cover pays 1.5%, which is $2,700 on top of the 2% Medicare levy.
Two details matter for higher earners in particular. Your assessment uses income for surcharge purposes, not salary, so bonuses, reportable fringe benefits from a novated lease, and salary sacrificed super contributions can lift you a tier. And because the charge is applied on assessment rather than withheld precisely, a PAYG taxpayer who has not lodged a Medicare levy variation declaration with their employer can face an unexpected bill.
If you want to sanity check take home pay and withheld amounts across the year, our tax deduction and pay calculators show how the underlying formulas work.
Who Has to Pay the Surcharge Based on Income and Family Status
Whether the MLS applies to you depends on three tests applied together: your income for surcharge purposes, your family status, and your days of appropriate hospital cover.
- Singles. You are treated as a single if you had no spouse and no dependants for the year. Your own income is tested against the singles thresholds.
- Couples. Combined income for surcharge purposes is tested against the family threshold, and each person is charged the couple's tier rate on their own taxable income plus reportable fringe benefits.
- Families and single parents. The family threshold applies, increased by $1,500 for each dependent child after the first.
- Not Medicare eligible. If you are a foreign resident or otherwise not entitled to Medicare benefits, the ATO exemption rules may remove the charge for those days.
Your dependants must also be covered by the policy. A parent with hospital cover for themselves but not their children can still be liable.
Part Year Hospital Cover and Suspended Policies: How Days Are Counted
The MLS is calculated on a daily basis, which is why part year cover produces a partial charge rather than a clean yes or no. The ATO counts the number of days in the income year that you and all your dependants were not covered by an appropriate hospital policy, then applies your tier rate to that fraction of the year.
A worked example: a single taxpayer in tier 1 on $110,000 who held hospital cover from 1 January to 30 June has 184 uncovered days. The charge is $110,000 multiplied by 1% multiplied by 184/365, which is roughly $555 rather than the full $1,100.
Suspended policies are the common trap. Insurers often let you suspend cover while travelling, but suspended days generally do not count as hospital cover for surcharge purposes. Check your statement, because it reports only the days you were genuinely covered.
Medicare Levy Surcharge Income Thresholds and Rates for Singles
For a single taxpayer with no spouse and no dependants, the ATO tests your own income for surcharge purposes against the singles thresholds set out earlier. Below the base tier, no surcharge applies. Above it, the rate steps up through 1%, 1.25% and 1.5% as your income crosses each tier boundary. The rate is not blended, so once your income exceeds a boundary the higher rate applies to your whole taxable income plus reportable fringe benefits, not just the part above the boundary.
It helps to separate the two charges. The Medicare levy is a 2% charge on taxable income that most Australian residents pay to help fund Medicare, with low income reductions and exemptions available. The surcharge is a separate additional charge of up to 1.5% aimed at higher earners without hospital cover. That is the core difference: the levy is near universal, while the surcharge is conditional and avoidable.
On $100,000 of taxable income, the Medicare levy is $2,000. You cannot choose to opt out of that 2%, though it is reduced or removed at low incomes and for people with a valid exemption category, such as certain foreign residents or people not entitled to Medicare benefits.
The only reliable way to avoid the Medicare surcharge is to hold an appropriate level of private patient hospital cover for yourself and all your dependants for the full year, or to have income in the base tier. Extras cover, ambulance cover and high excess policies do not help you avoid the Medicare surcharge. Legitimate income structuring, such as making deductible personal super contributions, can lower taxable income but does not always lower income for surcharge purposes.
Thresholds are indexed and announced by the ATO, so confirm the figures for the year you are lodging, including 2025-26, before you calculate. Not everyone pays the surcharge: most taxpayers fall in the base tier or hold qualifying cover.
In short, the two charges are different in base, rate and avoidability: the Medicare levy is a flat 2% charge on taxable income for most residents, while the surcharge is an additional tiered charge tested on income for surcharge purposes and days of hospital cover, as set out on the ATO's Medicare levy surcharge pages.
Family Income Thresholds and How Dependants Change Your Tier
If you had a spouse at any time during the year, or you maintained a dependent child, the family thresholds apply instead of the singles thresholds. The ATO combines both spouses' income for surcharge purposes to decide the tier, then charges each spouse the tier rate on their own taxable income plus reportable fringe benefits.
The family threshold increases by $1,500 for each dependent child after the first. A couple with three children therefore has a base tier threshold of $202,000 plus $3,000, or $205,000, for 2025-26.
Dependants for these purposes can include a spouse, a child under 21, or a full time student under 25 whom you maintain. Two practical points follow. Your children must be included on the hospital policy, and if you separated during the year, the ATO has specific rules for working out the period you had a spouse.
Medicare Levy vs the Surcharge: What Is the Difference?
The two charges are often discussed together but they work differently.
- Base. The levy applies to taxable income. The surcharge is charged on taxable income plus reportable fringe benefits, at a rate set by income for surcharge purposes, which adds back reportable fringe benefits, reportable super contributions, net investment losses and exempt foreign employment income.
- Rate. The levy is generally 2%. The surcharge is 1%, 1.25% or 1.5%.
- Who pays. Most resident taxpayers pay the levy. Only higher earners without appropriate hospital cover pay the surcharge.
- Avoidability. You cannot elect out of the levy, but the surcharge stops applying once appropriate hospital cover is in place.
Both are calculated by the ATO when your return is assessed, and both appear as separate lines on your notice of assessment, alongside any deductions you have claimed for the year.
Summary
Eligibility for the surcharge turns on three ATO tests: income for surcharge purposes, family status and dependants, and days of appropriate private patient hospital cover. Calculation is your tier rate applied to your taxable income plus reportable fringe benefits and apportioned across uncovered days. Records that support it are your private health insurance statement, spouse income details and dependant information. Deductit publishes plain English deduction guides and calculators you can use to check the formulas behind your own figures, and the ATO website holds the current thresholds for each income year.
Frequently asked questions
How can I avoid the 2% Medicare levy?
You cannot avoid the 2% Medicare levy by choice. It applies to most Australian resident taxpayers on their taxable income. The levy is reduced or removed only where you fall under the ATO low income thresholds, qualify for a reduction based on family income and dependants, or meet an exemption category such as not being entitled to Medicare benefits or holding a certified blind pensioner or Defence Force entitlement. What you can avoid, by holding appropriate hospital cover, is the separate surcharge of up to 1.5%.
Does everyone pay the Medicare levy surcharge?
No. Most taxpayers never pay it. You are only liable if your income for surcharge purposes exceeds the relevant singles or family threshold and you went without an appropriate level of private patient hospital cover for some or all of the income year. If either condition fails, no surcharge applies.
How much is the Medicare levy on $100,000?
On a taxable income of $100,000, the Medicare levy is 2%, or $2,000. Whether a surcharge sits on top depends on your income for surcharge purposes, which may exceed $100,000 once reportable fringe benefits, salary sacrificed super and net investment losses are added back, and on whether you held qualifying hospital cover.
How do I estimate my rate?
To estimate your rate, add your taxable income and the surcharge add backs, combine that with your spouse's equivalent figure if you had one, find your tier, then multiply by the fraction of days you were not covered. Our deduction finder helps you check the income figures behind that working.
What makes a hospital cover eligible to avoid the MLS?
What makes a hospital cover eligible to avoid the charge is set by the ATO: it must be private patient hospital cover from a registered Australian insurer, with an excess no greater than the ATO limits, covering you and every dependant for the days in question. Ambulance only and extras only policies are not eligible.
Where can I get more information?
For more information, check the ATO's Medicare levy surcharge pages, your insurer's annual tax statement, and Services Australia for Medicare entitlement questions. Our plain English Australian tax guides set out worked calculation examples.
Part of What Is the Medicare Levy? Rates, Rules and Surcharge